
AI·News & analysis
AI's funding problem just moved from the stock market to the bond market
Goldman Sachs tracks nearly $500 billion in AI-related debt issued in 2026 so far, with hyperscalers borrowing at 14 times 2024 levels to fund the AI buildout.
Tide
Ripple
Sci-fi
2/10
Reality
Shipping
The bill for building the future gets paid in bonds, not cash.How we rate
Goldman Sachs tracks nearly $500 billion in AI-related debt issued globally in 2026 so far, with hyperscalers accounting for about 40% of it.
The six biggest AI spenders issued $244 billion in bonds this year, 14 times 2024 levels. Their leverage ratios doubled in about six months, and credit spreads have widened as investors price in more risk. Goldman projects hyperscalers could issue over $1 trillion in new debt over the next few years to fund an estimated $5.8 trillion in AI spending through 2030.
What to know
- Goldman Sachs tracks nearly $500 billion in AI-related debt issued globally in 2026 so far, with hyperscalers making up about 40% of it.
- The six biggest AI infrastructure spenders issued $244 billion in bonds in 2026, 14 times what they issued in 2024 and double 2025's total.
- Hyperscaler leverage ratios doubled from 0.9x to 1.8x in roughly six months, and credit default swap spreads have widened as investors price in more risk.
- Goldman projects hyperscalers could issue more than $1 trillion in new debt over the next few years to fund an estimated $5.8 trillion in AI capital spending through 2030.
Building the AI future was supposed to be paid for with record profits. Increasingly, it's being paid for with borrowed money instead.
Goldman Sachs tracks nearly $500 billion in AI-related debt issued globally in 2026 so far. Hyperscalers, the handful of companies building most of the world's AI infrastructure, account for about 40% of that total.
How much has borrowing actually increased?
By the numbers, and these figures are striking: the six biggest AI infrastructure spenders, Microsoft, Amazon, Alphabet, Meta, Oracle, Nvidia, and SpaceX, issued $244 billion in bonds in 2026. That's 14 times what they borrowed in 2024, and roughly double their 2025 total.
- 2024 bond issuance (top 6 AI spenders): a small fraction of 2026's total.
- 2025 bond issuance: about half of 2026's level.
- 2026 bond issuance: $244 billion.
- Overall 2026 AI-related debt (all issuers): nearly $500 billion.
Why it matters: that trajectory isn't a gradual increase. Going from a baseline to 14 times that amount in two years reflects a fundamental shift in how these companies are choosing to finance AI infrastructure, moving decisively from cash and stock toward debt.
Are these companies taking on more risk?
The catch: yes, measurably so. Hyperscaler leverage ratios roughly doubled, from 0.9x to 1.8x, in about six months. Leverage ratio measures how much debt a company carries relative to its earnings, so a doubling in that short a window is a genuinely fast shift in financial risk.
Credit default swap spreads, essentially the market's price for insuring against a company defaulting on its debt, have also widened noticeably. That's a signal that bond investors are pricing in real uncertainty about whether this spending will pay off on schedule.
In real life think of a leverage ratio like your own debt-to-income ratio. Doubling it in six months would set off alarm bells for a personal loan officer, and it sets off similar alarm bells for the analysts pricing corporate bonds.
Why borrow instead of just paying cash?
Background: the scale of AI spending has simply outgrown what even the biggest tech companies can cover from operating cash flow alone. Goldman estimates hyperscalers face a combined $5.8 trillion in AI capital expenditures through 2030.
That figure consumes most of these companies' operating cash flow on its own, leaving debt as the main practical way to keep building data centers, chips, and power infrastructure at the pace AI demand currently requires. Equity markets have also grown more selective about funding pure infrastructure buildout, pushing more of the burden toward bond investors instead.
Can the bond market actually absorb this much debt?
What's next: it's getting harder. Goldman notes that where $75 billion in new issuance once stressed the bond market, just $25 billion now puts it on the defensive. That's a real, measurable shrinking of the market's cushion for handling large new debt offerings.
Who's affected: AI-related issuers now represent a growing share of investment-grade credit indices overall. That means the health of AI infrastructure spending isn't just a tech-sector story anymore, it's becoming a meaningful piece of the broader corporate bond market that pension funds, insurers, and everyday investors are exposed to through standard bond funds.
Hyperscaler bonds held by bond funds, insurers, pension funds, and similar institutions already represent roughly $520 billion of senior unsecured investment-grade corporate debt.
Beyond public bonds, insurance companies have become major buyers in the private placement market too, drawn to long-term, 15-to-20-year data center leases from highly rated hyperscalers that match well against their own long-term liabilities. Private credit funds, pensions, and asset managers lending directly add yet another layer of exposure spread across the broader financial system.
What happens if the AI payoff is slower than expected?
Why it matters: Goldman's central concern isn't that AI spending is wrong, it's about timing. Massive upfront infrastructure costs create real cash flow gaps if revenue and productivity gains from AI investments arrive later than currently projected.
If that gap widens, the consequences are concrete: credit rating downgrades, higher borrowing costs on future debt, or companies being forced to cut capital spending plans they've already publicly committed to. None of that requires AI to fail as a technology, just for the financial timeline to run slower than the borrowing already assumes it will.
That distinction matters. A useful, genuinely valuable technology can still leave investors exposed if the money borrowed to build it arrives faster than the revenue meant to pay it back.
Haven't we seen this kind of buildout before?
Background: the AI infrastructure boom has an obvious historical parallel: the late-1990s telecom and fiber-optic buildout. Telecom companies spent more than $500 billion between 1996 and 2000 laying over 80 million miles of fiber optic cable, betting that internet traffic growth would keep climbing indefinitely.
That bet didn't pay off on schedule. The industry ended up owing roughly a trillion dollars, much of which was never repaid, and bond investors recovered just over 20% of what they'd put in. Even four years after the crash, 85 to 95% of that fiber sat completely unused, later nicknamed "dark fiber."
The catch: there's an important difference worth naming. Analysts studying the comparison point out that hyperscalers have, until recently, funded most of their AI capital spending from strong internal cash flow rather than heavy debt, unlike telecom firms in 2000, which carried extremely high leverage from the start.
Goldman's new numbers suggest that gap is narrowing fast. That doesn't mean history is repeating exactly, but the distance between the two eras is closing faster than many analysts expected even a year ago.
Where's all this new debt coming from geographically?
Hyperscalers are also diversifying where they borrow, not just how much. Meta Europe is reportedly planning its first euro-denominated bond issuance this autumn, part of a broader shift toward Canadian dollar and euro markets alongside the traditional US dollar bond market.
Who's affected: that diversification spreads the search for buyers across more currencies and more investor bases, a sign issuance volume has grown large enough that relying on US dollar bond demand alone is no longer sufficient to fund the pace of spending these companies have planned.
What it means for you
- This is a financial markets story, not a product story. It won't change what AI tools you use directly, but it shapes the financial health of the companies building them.
- If you hold bond funds or a diversified retirement portfolio, you likely already have some exposure to hyperscaler AI debt, even without realizing it.
- Watch for credit rating actions on major AI infrastructure spenders. A downgrade would be a concrete signal that Goldman's timing concerns are materializing.
- The AI buildout's financial risk is now a mainstream market question, not a niche tech-sector concern, given how large a share of investment-grade credit these issuers represent.
The bottom line
The AI infrastructure boom has moved from being funded mostly by stock market enthusiasm to being funded increasingly by borrowed money, at a pace and overall scale that's genuinely new even by tech industry historical standards. Goldman's numbers don't predict a crisis, but they do describe a financial structure carrying real, steadily growing risk if AI's revenue payoff ultimately arrives slower than the debt underwriting it currently assumes it will.
Key facts
- 2026 AI-related debt issued
- Nearly $500 billion
- Top 6 spenders' 2026 bond issuance
- $244 billion, 14x 2024 levels
- Leverage ratio change
- 0.9x to 1.8x in ~6 months
- Projected 2030 AI capex
- $5.8 trillion combined
Got questions?
Quick answers, plain wordsHow much AI-related debt has been issued in 2026?
Nearly $500 billion, according to Goldman Sachs Research, with hyperscalers like Microsoft, Amazon, Alphabet, Meta, Oracle, Nvidia and SpaceX accounting for about 40% of that total.
How much have hyperscalers borrowed compared to past years?
The six biggest AI spenders issued $244 billion in bonds in 2026, 14 times their 2024 issuance and double what they issued in 2025.
Are hyperscalers taking on more financial risk?
Yes, measurably. Their leverage ratios roughly doubled, from 0.9x to 1.8x, in about six months, and credit default swap spreads have widened, signaling investors see more risk in the debt.
Why are companies borrowing instead of just using cash?
Goldman estimates hyperscalers face roughly $5.8 trillion in combined AI capital expenditures through 2030, which consumes most of their operating cash flow, leaving debt as the main way to fund construction at this scale.
Is the bond market able to absorb this much new debt easily?
It's getting harder. Goldman notes that where $75 billion in new issuance once stressed the market, just $25 billion now puts it on the defensive, a sign the market's cushion has shrunk.
What happens if AI revenue doesn't grow as fast as expected?
Goldman's core concern is timing: heavy upfront infrastructure spending creates cash flow gaps if revenue and productivity gains from AI lag behind. That could trigger credit rating pressure, higher borrowing costs, or forced cuts to spending plans.
Why are companies issuing debt in euros and Canadian dollars now?
It reflects hyperscalers diversifying their funding sources beyond the US dollar bond market, spreading the search for buyers across more currencies and investor bases as issuance volume keeps climbing.
How much more debt does Goldman expect going forward?
Goldman projects hyperscalers could issue more than $1 trillion in new debt over the next several years, with an estimated $400 billion in investment-grade bond issuance in 2027 alone.
SourcesFinancial Times
Topics and tagsFunding & deals, ai, finance, debt
Related stories
A startup wants satellites to think for themselves instead of waiting for instructions from Earth
Satlyt, founded by a former Google and SpaceX product manager, raised $8 million to build software that lets AI models run directly on satellites, cutting the need to send every decision back down to ground control.
Google is quietly funding Hollywood movies to make AI look less scary
Google partnered with talent agency Range Media Partners on 100 Zeros, a fund that co-produces films and TV shows aiming to show technology, especially AI, in a more optimistic light than shows like Black Mirror.
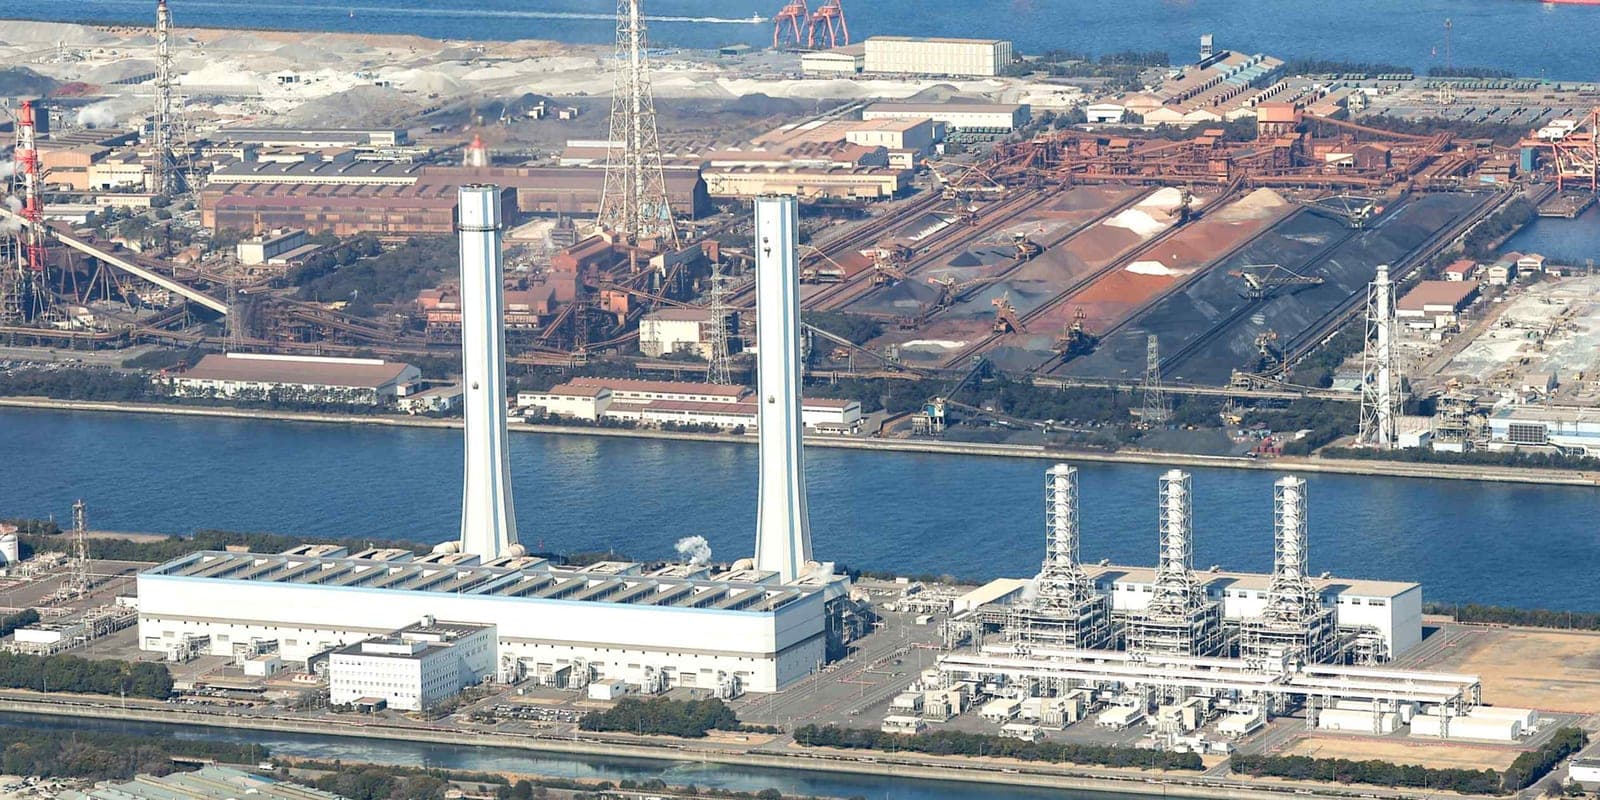
Japan's biggest power company is building its own gas plant just to feed one AI data center
JERA, Dell Technologies, and RHAELM signed a deal to build a $15 billion, 400-megawatt AI data center powered by its own dedicated energy supply near Tokyo, aiming to start operations around 2028.
More in brief
- arXiv limits researchers to two papers a month as AI drives submissions to a recordOct 2
- California will fine robotaxi companies that block first responders for over 30 minutesOct 2
- Microsoft launches real-time transcription and new voice models for AI voice agentsOct 1
- Apple's smart home hub reportedly launches October 13, with a camera that never records videoOct 1
- Cloudflare releases Clef, open-weight AI models that make yes-or-no decisions fastOct 1
- GrayKey maker reportedly found a way around the iPhone's Inactivity RebootOct 1